
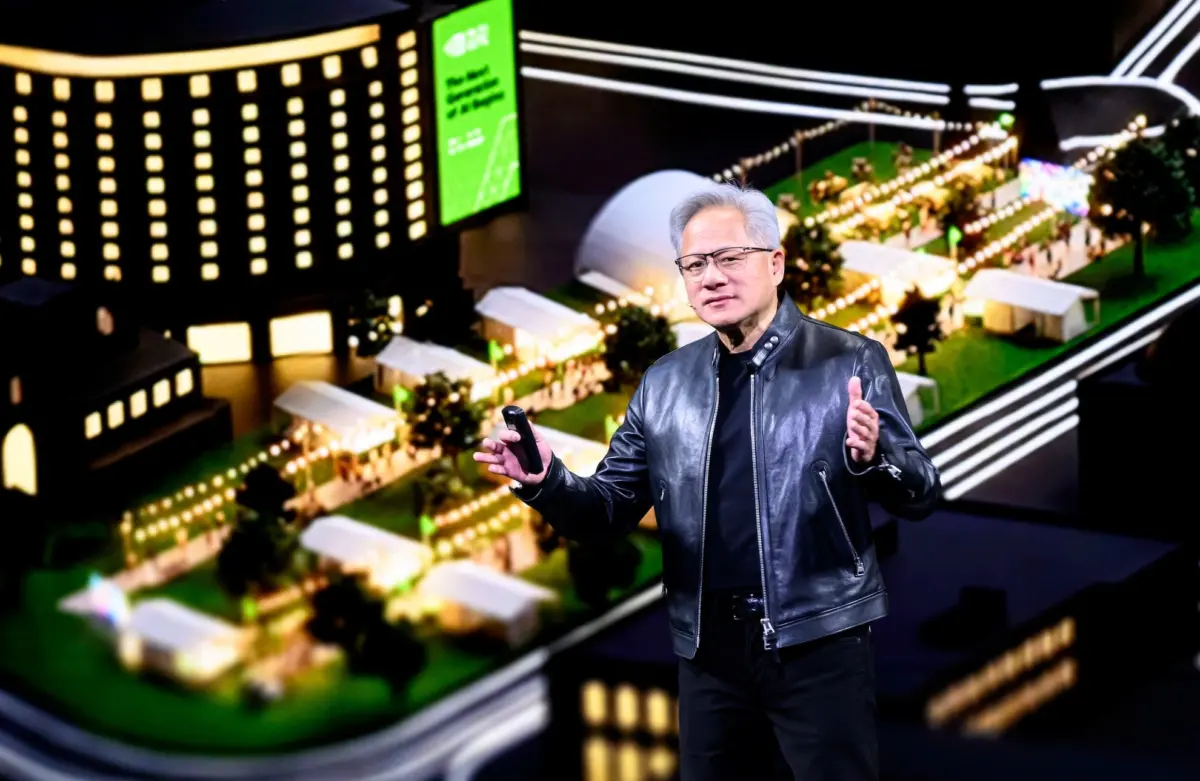
SAN FRANCISCO — In the high-stakes theater of modern technology, few executives command a room quite like Jensen Huang. Speaking on Thursday at the Goldman Sachs Communacopia + Technology conference, Nvidia’s co-founder, CEO, and chief evangelist delivered a masterclass in corporate confidence. Amid persistent market anxieties regarding soaring competition, capital expenditures, and potential market saturation, Huang painted a picture of unyielding, record-breaking dominance that he predicts will rocket the chipmaker’s revenues through the end of next year.
For an industry accustomed to cyclical boom-and-bust trajectories, Huang’s forecasts are staggering. Backed by booming order books, unprecedented structural integration across the global artificial intelligence ecosystem, and a product roadmap that redefines the concept of a "computer," Nvidia is steering full speed ahead into uncharted financial territory.
Main Facts: Redefining the Scale of Modern Computing
The core narrative of Huang’s address centered on a fundamental misunderstanding that he argues still plagues Wall Street and casual observers alike: the belief that Nvidia is merely a semiconductor manufacturer.
"Most people think Nvidia builds a chip. I mean, you need airplanes to ship what we build," Huang told attendees.
To illustrate the paradigm shift, Huang contrasted Nvidia’s historical roots with its current enterprise reality. Decades ago, the company invented the graphics processing unit (GPU), primarily selling consumer-grade hardware for roughly $399 to boost PC gaming performance. Today, a single Nvidia deployment is no longer a standalone silicon wafer in a plastic box; it is an industrial-scale data center infrastructure.
"One GPU now is not $399. It’s $8.5 million," Huang explained, detailing the architecture of advanced clusters. "That’s one GPU [system], all connected with NVLink, 2 million parts, right? 250,000 kilowatts. That’s a GPU, and we ship thousands of them."
The commercial engine driving this transformation is monumental. Nvidia’s flagship enterprise product—a massive computing system combining 36 Grace CPUs with 72 Blackwell GPUs (the GB200 NVL72)—is currently experiencing a blistering 27% month-to-month sales growth.
This momentum underpins Nvidia’s aggressive financial guidance. During its earnings call last month, the company projected a potential year-over-year revenue growth rate of 70% for the upcoming fiscal year. With analysts estimating that Nvidia will close its current fiscal year at approximately $400 billion in revenue, a 70% expansion translates to a jaw-dropping $680 billion next year.
Chronology: From PC Graphics to the Core of the AI Revolution
To understand how Nvidia reached a valuation and operational scale that rivals sovereign economies, it is helpful to trace the timeline of its strategic evolution:
- The Genesis (1993–2000s): Founded by Jensen Huang, Chris Malachowsky, and Curtis Priem, Nvidia focused heavily on 3D graphics for the burgeoning PC gaming market, ultimately inventing the GPU in 1999 with the GeForce 256.
- The Software Pivot (2006): Nvidia introduced CUDA, a parallel computing platform and programming model. At the time, this was a costly, speculative gamble that alienated traditional financial analysts, but it laid the foundational software layer that would later allow GPUs to process complex mathematical calculations far beyond rendering graphics.
- The Deep Learning Explosion (2012–2020): Researchers realized that CUDA-enabled GPUs were uniquely suited for training deep neural networks. AlexNet’s victory in the 2012 ImageNet competition using Nvidia GPUs sparked the modern AI boom, turning the company into the undisputed hardware supplier for early AI research.
- The Generative AI Gold Rush (2022–Present): The launch of OpenAI’s ChatGPT in late 2022 transformed AI from a niche academic pursuit into a global economic imperative. Hyperscalers, enterprises, and sovereign states began hoarding Nvidia H100, B200, and Blackwell systems, driving Nvidia’s market capitalization into historic territory.
- The Goldman Sachs Address (September 2026): Jensen Huang takes the stage at the Goldman Sachs Communacopia + Technology conference, doubling down on 70% projected growth for the following year and defending the company’s deeply interconnected business model against rising structural skepticism.
Supporting Data: Omnipresence Across the Global AI Supply Chain
Skeptics frequently question whether demand can realistically sustain itself given the sheer capital expenditures poured into AI infrastructure. Huang’s response is rooted in data visibility. Because Nvidia chips power virtually every major foundational model in existence, the company maintains a God’s-eye view of the global technology landscape.
"Nvidia runs every model. Every single lab can use us," Huang noted, explicitly naming competitors and partners alike, including OpenAI, Anthropic, Google, and a wide array of open-weight model developers. "We are a foundational platform of the AI ecosystem, foundational platform of the AI industry."
This omnipresence goes far beyond the silicon foundries of TSMC or high-bandwidth memory suppliers. Nvidia tracks the physical infrastructure of the planet in real time:
- Global Real Estate and Power Tracking: "We’re tracking every single gigawatt of land, power, shell around the world. Literally everything on the planet," Huang said, defining a "shell" as the physical concrete structure of a data center before computing hardware is installed.
- Ecosystem Feedback Loops: Through continuous communication with neocloud providers, Original Equipment Manufacturers (OEMs), hyper-scale cloud giants, and AI-native startups, Nvidia operates at the nerve center of tech industry intelligence. "We’re working with everybody, and so we kind of know where everything is," he asserted.
Official Responses: Addressing the "Circular Financing" Debate
With immense market power comes intense scrutiny. Financial analysts and industry commentators have increasingly raised alarms regarding Nvidia’s investment practices—specifically, whether the company engages in "circular financing" akin to the practices that preceded the collapse of telecommunications giants like Lucent Technologies during the dot-com era. These concerns stem from instances where Nvidia invests venture capital into emerging AI startups or cloud providers, which subsequently turn around and allocate those funds toward purchasing Nvidia GPUs.
Huang met these inquiries head-on with characteristic candor and humor.
"Well, it’s not circular because we put a little bit of money in, and a lot of money comes back," Huang quipped. He added with a laugh: "I look at the spreadsheet, we put in $1 and $100 comes back in. Is that circular? If that is, let’s do more of that."
Jokes aside, the CEO pivoted to rigorous risk management. He insisted that before Nvidia commits a single dollar of venture capital to an ecosystem partner, the recipient must demonstrate tangible, revenue-generating contracts with downstream customers.
"I’ve seen $100 billion worth of such contracts," Huang stated. "I’m not taking any risks. […] I need a sure thing." By tethering its investments to verified commercial demand rather than speculative promises, Nvidia argues its financial arrangements are insulated from the vulnerabilities that plagued past tech bubbles.
Implications: Navigating the Fine Line Between Dominance and Disruption
As Nvidia looks toward a horizon that could feature nearly $700 billion in annual revenue, the broader technology sector must grapple with the implications of an AI economy heavily reliant on a single hardware titan.
1. The Rise of Alternative Silicon
Despite Nvidia’s formidable moat, competitive pressures are mounting from all angles. Hyperscalers like Amazon (Trainium/Inferentia), Microsoft (Maia), and Google (TPUs) continue to design and deploy custom silicon to reduce their dependency on expensive GPU clusters. Meanwhile, dedicated AI chip competitors are making high-profile waves: Cerebras recently secured landmark funding and deployment wins, while specialized low-latency inference startup Etched crossed into multi-billion-dollar valuations.
2. The Efficiency Paradox
A major long-term variable for Nvidia is software optimization and inference efficiency. Much of the current market growth is propelled by AI-native startups raising gargantuan venture rounds and immediately plowing that capital back into computing infrastructure. As the AI industry matures, enterprises will inevitably demand greater cost efficiencies, fewer tokens per query, and leaner architectures. If software breakthroughs drastically reduce the hardware requirements needed to run advanced models, hardware demand could theoretically normalize.
3. A Foundational Pillar—For Now
History teaches that no tech monopoly remains unchallenged forever. Disruptions are an immutable law of Silicon Valley. Yet, for the foreseeable future, Nvidia remains the undisputed tollbooth on the digital turnpike of the artificial intelligence revolution.
Whether Jensen Huang’s crystal ball is as clear as he claims will be tested in the coming quarters. But as long as the world continues to demand faster models, larger clusters, and ever-expanding data centers, Nvidia’s unprecedented machinery shows no signs of slowing down.
