
By Global Tech & Imaging Desk
The landscape of digital imaging is undergoing a profound structural shift. While legacy camera manufacturers in Japan celebrate a modest, multi-year resurgence in traditional mirrorless and DSLR sales, a rapidly expanding sector is quietly rewriting the rules of the global market.
According to newly published intelligence data from IDC, the worldwide "handheld smart camera" market—encompassing action cameras, 360-degree cameras, and intelligent gimbal-mounted vlogging devices—surged by an astonishing 83% year-over-year in 2025. Total shipments reached 16.65 million units, driving revenues past 46 billion yuan (approximately $6.875 trillion at current exchange rates, reflecting broader economic tracking metrics in the sector), marking an 86% revenue spike compared to 2024.
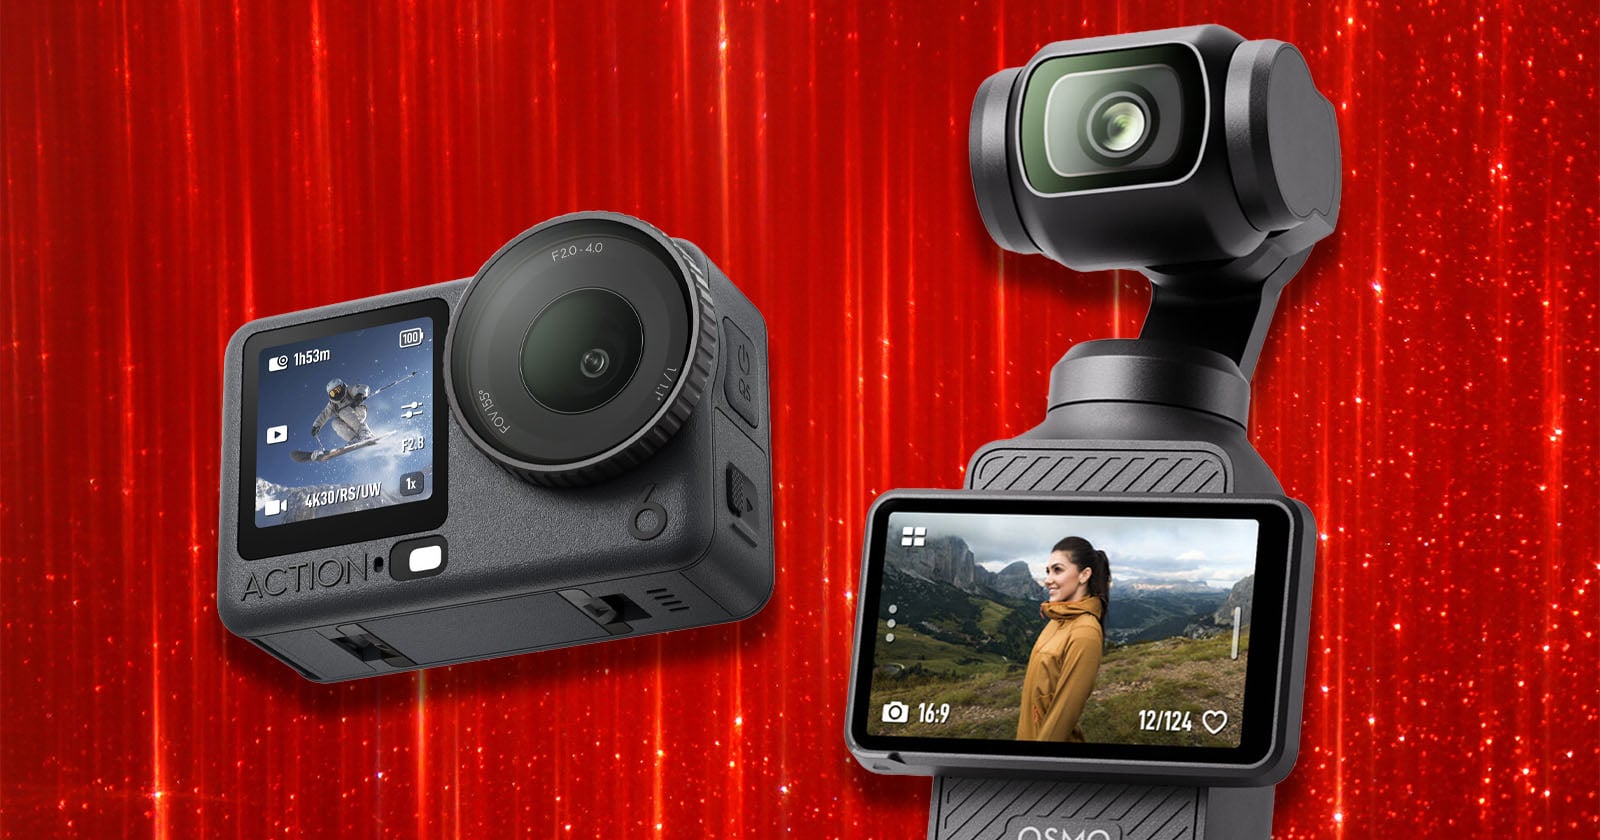
At the center of this seismic shift are Chinese tech giants DJI and Insta360. In 2025, market leader DJI single-handedly shipped 10.4 million handheld cameras—a milestone that not only breaks the 10-million-unit threshold for the company for the first time, but also allows a single manufacturer to outpace the combined output of every single Japanese camera maker tracked by the Camera & Imaging Products Association (CIPA).
As content creation culture reaches an all-time high, industry analysts are forced to ask: Are we witnessing the dawn of a new imaging era, or simply the peaceful coexistence of two fundamentally different photographic philosophies?
Main Facts: The Numbers Behind the Shift
To understand the scale of the current imaging boom, it is necessary to examine the stark contrast between the traditional photographic market and the modern handheld smart camera ecosystem.
- The Handheld Smart Camera Explosion: IDC data indicates the market hit 16.65 million units in 2025, up 83% from the previous year. Market analysts project this trajectory will continue, pushing total shipments to an estimated 40 million units annually by 2030.
- The Titans of Output: DJI crossed the 10.4-million-unit mark in 2025. Competitor Insta360 followed closely with 3.4 million units shipped. Combined, these two companies accounted for roughly 13.8 million devices.
- The Traditional Counterpart: According to CIPA—which aggregates data primarily from Japanese legacy manufacturers like Canon, Nikon, Sony, and Fujifilm—total digital camera shipments in 2025 reached 9.44 million units. This included interchangeable-lens systems (mirrorless and DSLR) as well as fixed-lens compacts, representing the industry’s fourth consecutive year of growth and its highest total since 2019.
- The Mirrorless Comparison: Focusing specifically on the mirrorless and DSLR segment, CIPA members shipped approximately 6.1 million units in 2025. This means DJI and Insta360 combined shipped more than twice as many handheld devices as the entire global mirrorless industry produced.
Chronology of the Divide: How We Got Here
The divergence between traditional optical systems and consumer-grade smart cameras did not happen overnight. It is the culmination of a decade-long evolution in sensor technology, mobile processing power, and shifting consumer demographics.
2015–2019: The Action Cam Monopoly and Mobile Integration
For years, companies like GoPro dominated the action sports niche, proving that consumers desired rugged, wearable documentation tools. However, traditional camera makers remained focused on high-margin interchangeable-lens systems, viewing compacts and action cameras as low-end consumer electronics rather than serious imaging tools. During this period, drone leader DJI recognized the potential of motorized stabilization, pivoting its gimbal technology into handheld form factors with the introduction of the original Osmo Pocket in late 2018.
2020–2023: The Pandemic Pivot and the Content Boom
The COVID-19 pandemic catalyzed an unprecedented surge in digital content creation. Stuck indoors or seeking outdoor hobbies, consumers demanded lightweight, easy-to-use tools for vlogging, streaming, and social media production. While supply chain disruptions battered traditional camera manufacturers—pushing CIPA shipment numbers to historic lows in 2023—agile smart camera developers rapidly iterated on software, artificial intelligence tracking, and pocket-sized form factors.
2024–2025: Exponential Acceleration
By 2024, the market had found its stride. IDC metrics show that the handheld camera sector began growing at an exponential clip. By 2025, year-over-year growth hit an astonishing 83%. Consumers embraced devices like the DJI Osmo Pocket series, the Insta360 X-series, and newer compact variants like the Osmo Nano and Insta360 Luna series. Meanwhile, pioneers like GoPro saw their market share steadily erode, struggling to maintain profitability in a landscape heavily disrupted by aggressive Chinese manufacturing and rapid innovation cycles.
Supporting Data: Volume vs. Value
While the unit sales figures heavily favor handheld smart cameras, industry experts caution against a simplistic "quantity over quality" narrative. The economic realities of the two markets reveal stark differences in pricing models, profit margins, and consumer intent.
| Metric | Handheld Smart Cameras (DJI, Insta360, GoPro, etc.) | Traditional Digital Cameras (CIPA / Japanese Makers) |
|---|---|---|
| 2025 Total Unit Shipments | 16.65 million units | 9.44 million units |
| Market Growth Rate (YoY) | +83% | Moderate consecutive growth |
| Average Device Cost | Generally lower ($300 – $800) | Significantly higher ($1,000 – $3,000+ body-only) |
| Accessory Ecosystem | Integrated lenses, minimal additional lens purchases | High-margin interchangeable lenses costing hundreds or thousands more |
| Price Sensitivity | High; a $50 price variance heavily impacts consumer choice | Low; minimal impact on high-end, professional kit purchases |
As CineD and other industry analysts point out, comparing a $770 Insta360 Luna Ultra or a compact DJI action camera directly to a full-frame mirrorless professional rig is an apples-to-oranges comparison. Traditional photography remains a high-margin, high-investment field where professional users build extensive lens repertoires over years. Conversely, the smart camera market operates on high-volume, rapid-turnover consumer cycles where accessibility, stabilization, and immediate social sharing capabilities reign supreme.
Official Responses and Industry Reactions
As the numbers from IDC and CIPA circulate through boardrooms in Tokyo, Shenzhen, and San Francisco, industry stakeholders have begun reacting to the shifting balance of power.
Legacy manufacturers have largely maintained a diplomatic stance, publicly emphasizing that the expansion of the broader imaging market benefits the entire ecosystem. Executives from traditional brands argue that smartphone users and smart camera owners often develop a deeper interest in photography, eventually graduating to dedicated mirrorless systems for professional work.
However, behind closed doors, the pressure is mounting. Japanese camera brands have increasingly pivoted toward high-end, premium-priced full-frame bodies and cinematic cinema lines, effectively abandoning the low-end compact camera market that smartphones and action cams swallowed years ago.
Meanwhile, the dominant players in the handheld space face unique geopolitical and regulatory hurdles. DJI, despite its staggering 10.4 million unit milestone, continues to navigate complex regulatory scrutiny and potential restrictions with the Federal Communications Commission (FCC) in the United States—one of the most lucrative consumer technology markets in the world. How these ongoing regulatory headwinds will impact DJI’s international distribution and shipment growth in the coming fiscal year remains a central question for industry watchers.
Implications: Coexistence, Competition, and the Future
What does this seismic shift mean for the future of how humanity captures memories, art, and media?
First and foremost, industry analysts stress that one market’s success does not require another’s failure. The narrative of "Handheld Smart Cameras vs. Traditional Mirrorless Cameras" is a false dichotomy. Modern creators frequently own both: a pocket-sized Insta360 or DJI gimbal for spontaneous daily vlogging, travel, and extreme sports, alongside a traditional interchangeable-lens camera for deliberate artistic composition, low-light portraiture, and professional client work. Buying an action cam does not render a professional cinema rig obsolete.
Second, the unprecedented dominance of DJI and Insta360 highlights a broader trend in consumer electronics: Chinese hardware manufacturers have mastered the art of vertical integration, rapid software deployment, and aggressive pricing. While American pioneer GoPro struggles to find a financial foothold after posting multi-million dollar quarterly losses, its Asian competitors continue to push the boundaries of what a pocket-sized device can achieve through computational photography and AI-driven stabilization.
Finally, looking toward the horizon of 2030—when IDC predicts the handheld smart camera market will swell to 40 million units annually—we must ask whether these devices will eventually evolve into full-fledged replacements for traditional cameras outside of specialized professional niches. As sensors grow larger, optics improve, and software automation bridges the gap between consumer convenience and professional output, the boundary line between "smart camera" and "pro imaging tool" is bound to blur even further.
For now, the imaging world is big enough for both worlds: the quiet, deliberate craft of optical glass and interchangeable sensors, and the lightning-fast, stabilized world of the handheld smart camera revolution.
