
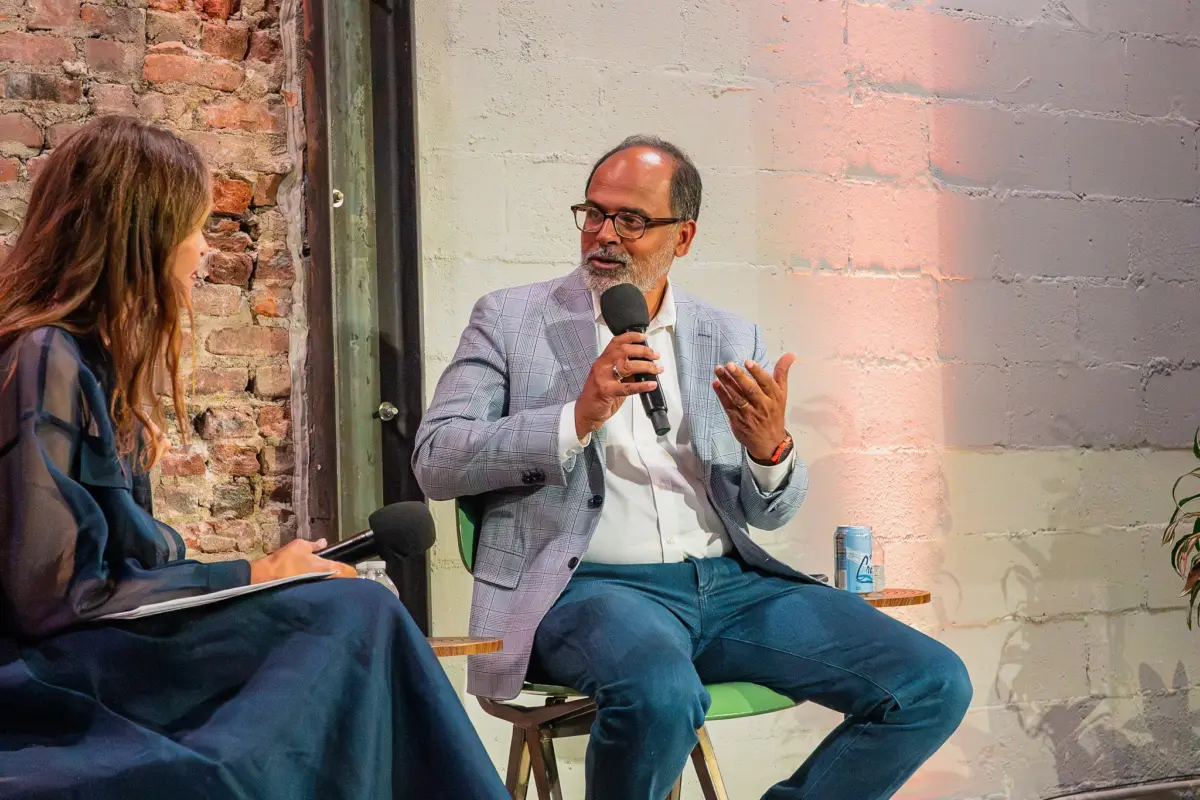
NEW YORK — In an ecosystem dominated by self-styled visionaries, podcast hosts, and hyperactive X (formerly Twitter) posters, Devin Parekh cuts an entirely different profile. For 26 years, Parekh has co-run Insight Partners, a heavyweight global investment firm with a staggering $90 billion in assets under management (AUM). Yet, while peers scramble for the limelight, Parekh and Insight largely choose to operate in the shadows, letting their portfolio perform the talking.
During a candid sit-down interview with TechCrunch at the StrictlyVC event in New York City, Parekh pulled back the curtain on the quiet mechanics of a top-tier multi-strategy firm. Addressing everything from the artificial intelligence gold rush and the reality of concentrated portfolios to missed deals like Legora and the looming wave of trillion-dollar IPOs, Parekh offered a masterclass in long-term venture capital survival.
Main Facts: Navigating the AI Era and Multi-Strategy Discipline
The venture capital landscape has undergone a seismic shift, dominated almost entirely by the generative AI explosion. However, Insight Partners has successfully avoided the herd mentality that plagues many modern venture capitalists. While firms race to pile billions into frontier AI labs, Insight has maintained a diversified, stage-agnostic strategy spanning early-stage venture, growth equity, and buyouts.
Key takeaways from Parekh’s masterclass include:
- The AI Risk Calculus: Parekh acknowledges the existential concerns surrounding open-source models falling into rogue hands to manufacture biological weapons. However, he weighs these risks against the staggering societal upsides, such as compressing drug discovery timelines and revolutionizing healthcare diagnostics.
- The Portfolio Heavyweights: Insight boasts significant positions in major technology players, including Databricks, Wiz, and stakes in both OpenAI and Anthropic—a dual-investment strategy that was once taboo in early-stage venture capital.
- Capital Return Realities: Over the past two years, Insight has quietly returned over $20 billion to its Limited Partners (LPs) via strategic sales and initial public offerings (IPOs), emphasizing that delivering real liquidity (DPI, or Distributed to Paid-In capital) remains the ultimate mandate of the asset class.
- Geographic Reality: While artificial intelligence infrastructure talent remains tightly clustered in San Francisco, vertical AI applications—such as financial technology centered around New York-based Ramp—prove that talent density depends entirely on the specific industry vertical.
Chronology: From the 2021 Froth to the Trillion-Dollar IPO Wave
To fully understand Insight Partners’ current positioning, it is necessary to examine how the firm has weathered historical market cycles and adapted its deployment strategy over decades.
2021: The Valuation Peak
At the height of the zero-interest-rate policy era, venture valuations ballooned to unsustainable heights. Insight observed a market where follow-up financing rounds offered almost zero incremental data to justify soaring prices. Recognizing this inflation early, the firm adjusted its playbooks. Rather than chasing bloated growth rounds, Insight leaned heavily into earlier-stage investments where writing smaller checks ($20 million to $25 million instead of $500 million) minimized exposure while preserving the option to double down on breakout winners like cybersecurity unicorn Wiz.
2024: The Buyout Drought and Strategic Pivots
By 2024, high interest rates, unreceptive debt markets for enterprise software, and compressed exit multiples ground major software buyouts to a halt. Insight shifted its capital deployment accordingly. Buyouts effectively paused, and the firm turned its focus toward identifying inflection points within its existing portfolio.
A prime historical example of this patient chronologic strategy is security firm Armis. After losing the initial deal to Sequoia Capital, Insight kept the relationship warm with a modest $5 million check. Eighteen months later, Insight bought out the entire cap table with a nine-figure check—ultimately guiding Armis to a massive $7 billion acquisition by ServiceNow.
The Present: The Approaching IPO Wave
As the industry moves forward, the timeline has compressed rapidly. Companies like Anthropic, having scaled faster than legacy enterprise software giants like Salesforce within a mere four-year window, are preparing to test public markets alongside OpenAI and SpaceX. These impending public listings threaten to redefine public market expectations for tech growth over the next 18 months.
Supporting Data: The Math of Concentration vs. Diversification
Venture capital is a game of outliers, but the degree to which firms should concentrate their capital remains a fierce point of debate. Data from early 2026 indicates that OpenAI and Anthropic commanded roughly half of all venture capital dollars deployed in the first half of the year.
- The Concentration Trap: Parekh notes that some newly minted funds are raising their entire capital bases on a single pitch: allocating 35% to 40% of their fund into just one or two mega-labs. While exceptions like Founders Fund and Thrive Capital have executed concentrated strategies with great success, historical market data warns that extreme concentration breaks down over a ten-fund horizon.
- Fund Scale Economics: Operating on Fund XIII, Insight manages risk through disciplined diversification. If 25% of a massive fund were tied up in a single asset like Anthropic, short-term returns might sparkle, but over decades, long-horizon investing continuously rewards portfolio balance.
- The Liquidity Metric: DPI has become the primary battleground for venture capital performance. With many first- and second-time fund managers failing to return capital from the 2021–2023 vintages, LPs are heavily penalizing firms that fail to realize cash, regardless of paper markups. Parekh urges managers to de-risk portfolios by taking initial cost bases off the table even when companies show promising trajectory.
Official Responses and Industry Perspectives
During his conversation at StrictlyVC, Parekh did not shy away from addressing controversial industry topics, offering candid assessments of missed opportunities, generational divides within VC, and the ethics of backing competing giants.
On Missing Out on Legora
When asked why Insight lost the buzzy European AI legal-tech startup Legora to General Catalyst—despite partner Jeff Horing flying directly to Stockholm to pitch the founder—Parekh remained remarkably pragmatic.
"I don’t know the specific reason, but I think they sold their value proposition better than we sold ours that time. There are plenty of examples where it went the other way. It’s a big world; we don’t need to win every deal."
On Backing Both OpenAI and Anthropic
The old venture dogma dictated that investing in direct competitors was a cardinal sin, signaling conflicts of interest and raising governance red flags. Parekh explained that Insight’s internal debates were less about moral conflict and more about investment timing.
"Once you’re at a later stage, off the board, not driving governance, you’re just buying a great stock. We saw OpenAI as the dominant consumer play and Anthropic as having a clear enterprise strategy… As these companies needed to raise $30 billion to $100 billion, they stopped being able to dictate exclusivity."
On Generational Divides in Tech Trends
Highlighting the shifting perspectives within the venture ecosystem, Parekh contrasted his own measured skepticism with the enthusiasm of younger investors, including his 23-year-old son. While his son views physical AI and robotics as the hottest frontier space—and views Parekh’s hesitation as archaic—Parekh characterizes current physical intelligence startups as glorified "science projects" awaiting the true arrival of mass robotics adoption curves.
Implications: What Parekh’s Insights Mean for the Future of Tech Investing
The philosophies championed by Devin Parekh and Insight Partners carry profound implications for founders, limited partners, and fellow venture capitalists alike.
- The End of "Vibes-Based" Investing: As markets mature past the speculative excesses of the early 2020s, LPs are demanding rigorous financial discipline. Firms that rely purely on social media noise and podcast appearances are facing increasing scrutiny over actual cash distributions. The era of the loud, omnipresent VC is being challenged by disciplined operators who treat venture capital as an institutional asset class rather than a lifestyle brand.
- Founders Face Valuation Reality Checks: With elite investors advising founders to de-risk 10% to 20% of their holdings when frothy valuations present themselves, founders must realize that compound growth mathematical limits apply even to AI darlings. As Parekh bluntly notes: "You can’t compound $40 billion at 50% every two months for two years without becoming the world economy. That math doesn’t work."
- The Public Markets Reopen: The anticipated public debuts of generational AI companies over the next year and a half will serve as a definitive stress test for public market appetite. If public investors absorb multi-trillion-dollar tech listings smoothly, it will clear the path for the broader tier of venture-backed companies to finally achieve liquidity, unfreezing a choked exit market and returning capital back to LPs to restart the funding flywheel.
Ultimately, Insight Partners proves that quiet execution, a commitment to global talent mapping, and an unwavering focus on portfolio liquidity remain the most enduring recipes for success in an industry perpetually prone to cyclical hysteria.
